Locating the income figure and calculation method used on your denial notice
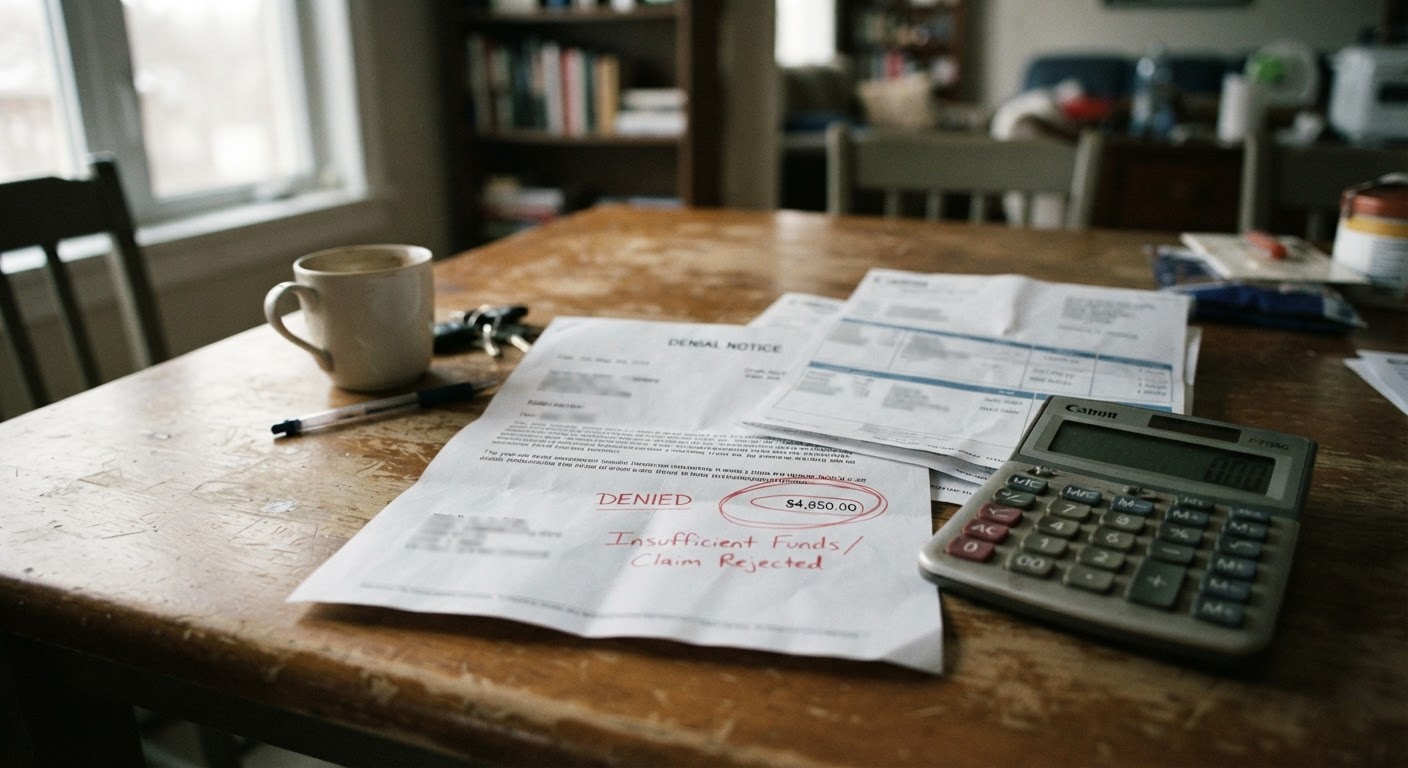
Every denial or termination notice that involves an income test should show three things somewhere on the page: the income figure the agency used, the time period that figure represents (weekly, biweekly, monthly, or annual), and a reference to the income limit it was compared against. These are sometimes on the first page, sometimes on an attached worksheet, and sometimes only referenced by a code that requires you to call and ask what it means. Start by finding all three. If you can only find the final number and not the method, that itself is useful information for the next step, because you cannot check a calculation you cannot see.
Look specifically for language like “gross monthly income,” “countable income,” “converted income,” or “average income over [a stated period].” Agencies rarely calculate benefits using your income exactly as it appears on a single pay stub. Instead, they convert whatever pay period you’re paid on into a monthly figure, because most benefit programs run on monthly income limits. That conversion step is where errors most often creep in, and it’s also the step that is easiest for you to redo independently once you know which formula was applied.
If the notice doesn’t specify the method, request the calculation worksheet or budget sheet from the case record. You are generally entitled to see how a number affecting your eligibility was produced, and asking for it in writing creates a record that you asked, which matters if you later need to show you acted promptly and in good faith.
Common conversion errors: weekly-to-monthly, biweekly-to-monthly, and averaging mistakes
Most income calculation errors fall into a small number of predictable categories. Knowing them in advance makes it much faster to spot which one happened to you.
Weekly-to-monthly conversion
If you are paid weekly, the standard conversion multiplies your weekly gross pay by 4.33 (the average number of weeks in a month), not by 4. Using a flat multiplier of 4 understates your income, which usually works in your favor, but agencies sometimes make the opposite error: multiplying a single unusually high or low week by 4.33 without checking whether that week was representative. If your notice shows a monthly figure that looks like it came from one specific week rather than a pattern of weeks, that’s worth flagging.
Biweekly-to-monthly conversion
If you are paid every two weeks, the standard conversion multiplies your biweekly gross pay by 2.15, not by 2. There are 26 biweekly pay periods in a year, not 24, so multiplying by 2 understates annual and monthly income, while some caseworkers mistakenly use 2 anyway. Conversely, mistaking a biweekly pay stub for a semimonthly one (paid twice a month, 24 times a year) and applying the wrong multiplier in the other direction is a common transposition error, especially when pay stubs don’t clearly label the pay schedule.
Averaging mistakes
When income varies week to week, agencies are typically supposed to average a representative sample of recent pay stubs, often four to eight weeks, rather than relying on a single stub. Averaging errors happen when: only one or two stubs were used instead of a full sample; a stub that included an atypical event, like overtime, a bonus, a retroactive correction, or a pay period with fewer worked hours than usual, was included without adjustment; or stubs from a period before a documented change in hours or wage rate were used instead of current ones.
Gross versus net confusion
Most programs count gross income before deductions, not take-home pay. If your pay stub shows a “net pay” figure and that number was used as though it were gross, the calculation may not match your gross earnings box, and the discrepancy is easy to demonstrate side by side.
Wrong income counted
Occasionally the error isn’t in the conversion but in the inputs: income from a household member who shouldn’t be counted, income from a job you no longer hold, or a one-time payment treated as ongoing income. These aren’t conversion errors, but they show up the same way, as a monthly figure that doesn’t match your actual current earnings, so it’s worth checking the source line items, not just the math.
How to reconstruct the calculation yourself using your actual pay records
Once you know or suspect which conversion method should apply, rebuild the number from scratch using your own pay stubs, in a way you can show someone else and that they can check.
Start by gathering the same pay stubs, or the same type of record, the agency likely used or should have used. If the notice references a specific period, “the four weeks ending [a date],” pull those exact stubs. If it doesn’t specify, use your most recent full pay periods, since that is the general default.
List the gross pay for each stub separately, not just a total. This lets you check whether any single period is being treated as if it were typical when it wasn’t. Note anything unusual on any stub: overtime, a missed shift, a holiday payout, a correction from a prior pay period, or a rate change partway through.
Apply the conversion factor by hand:
Weekly pay: total the gross pay for a representative sample of weeks, divide by the number of weeks to get a weekly average, then multiply by 4.33.
Biweekly pay: total the gross pay for a representative sample of biweekly periods, divide to get an average, then multiply by 2.15.
Semimonthly pay (paid on set dates like the 1st and 15th): multiply the average per-period gross by 2, since there are 24 semimonthly periods in a year.
Compare your result to the figure on the notice. Write down both numbers and the difference. If they don’t match, you now have a specific, demonstrable discrepancy rather than a general objection, which is far more persuasive and far faster for a caseworker to act on.
If your pay varies significantly and there’s no clean “representative” period, say so directly rather than picking whichever sample produces the most favorable number. Agencies are generally required to use a fair and representative sample, and if you can show the sample used wasn’t representative, that’s a legitimate basis for correction even if you can’t propose a single obviously correct substitute yet.
Whether to request a correction informally or file a formal appeal
These aren’t mutually exclusive, and in most cases you should do both, because they protect you in different ways.
An informal request, a call or written note to your caseworker or the agency’s error-correction line, is often faster. Many income calculation errors are clerical: a wrong multiplier, a mistyped digit, a stub from the wrong month. If the error is that clear, an informal request can sometimes get it fixed within days, without waiting for a formal appeal hearing to be scheduled.
However, an informal request does not stop your appeal deadline from running, and it does not guarantee the agency will respond in writing or at all. If you rely only on an informal call and the person you spoke with doesn’t act on it, you can lose your right to appeal simply because time ran out while you were waiting for a callback.
The safer sequence is: file the formal appeal first, or at the same time, to preserve your deadline, and separately send a written correction request explaining the specific error. If the informal correction resolves the issue, the appeal becomes unnecessary and can typically be withdrawn or will close on its own once the case is corrected. If it doesn’t resolve quickly, your appeal is already in motion and you haven’t lost anything by also having asked informally.
Check your notice for the exact appeal deadline and how the appeal must be filed, since these details vary by program and by state, and missing the stated method (for example, filing only by phone when written filing is required) can itself cause delay.
What to include in a written request to recalculate before your appeal deadline
Whether you send this as a standalone correction request, as an attachment to your appeal, or as both, a written recalculation request should be specific enough that someone unfamiliar with your case could redo the math from what you’ve provided. Include:
Your name, case or application number, and the date of the notice you’re responding to, so it’s routed to the right file without delay.
The exact figure the notice used and where you found it, quoting the language from the notice (“the notice lists gross monthly income of [amount], based on [stated period]”).
Copies of the pay stubs you used to recalculate, clearly labeled with dates, not just totals.
Your own calculation, shown step by step, including which conversion factor you used and why (for example, “paid biweekly, so gross pay per period multiplied by 2.15”).
A plain statement of the specific error you believe occurred, framed as a fact to check rather than an accusation: “the notice appears to use a multiplier of 2 rather than 2.15 for biweekly pay” or “the sample period included one week of overtime that isn’t part of my regular schedule.”
A clear request: that the income figure be recalculated using the attached records, and that you receive a written response before your appeal deadline if possible, or written confirmation of what was corrected if the case is adjusted.
Keep a copy of everything you send and note the date you sent it. If you’re mailing it, consider a method that gives you proof of delivery. If your appeal deadline is close, don’t wait for a response before filing the appeal itself; send the correction request and file the appeal in the same window, and let the two processes run in parallel.